

Dear fellow investors,
The long and winding road that leads to your door
Will never disappear, I’ve seen that road before
It always leads me here, lead me to your door
The wild and windy night that the rain washed away
Has left a pool of tears, crying for the day
Why leave me standing here?
Let me know the way
Many times I’ve been alone, and many times I’ve cried
Anyway, you’ll never know the many ways I’ve tried
-The Beatles, “The Long and Winding Road”
——–
If you don’t know this by now, investing in common stocks is a marathon. In effect, it is a “long and winding road!” Our job is to lead our investors to success in the “winding.” Most investors in US common stocks have found their way on the most spectacular gravy train in the history of common stock investing. This gravy train has been terrific for 17 years since the stock market bottomed in 2009. Therefore, the long road has been dramatically less “windy” over these years. Why has the long and winding road of the stock market been less winding?
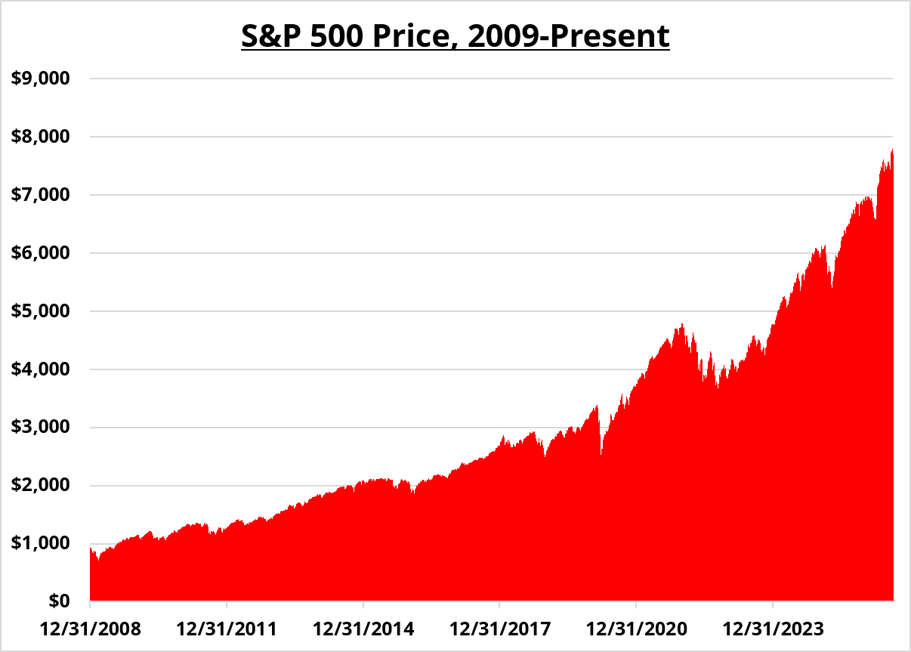
Source: Bloomberg.
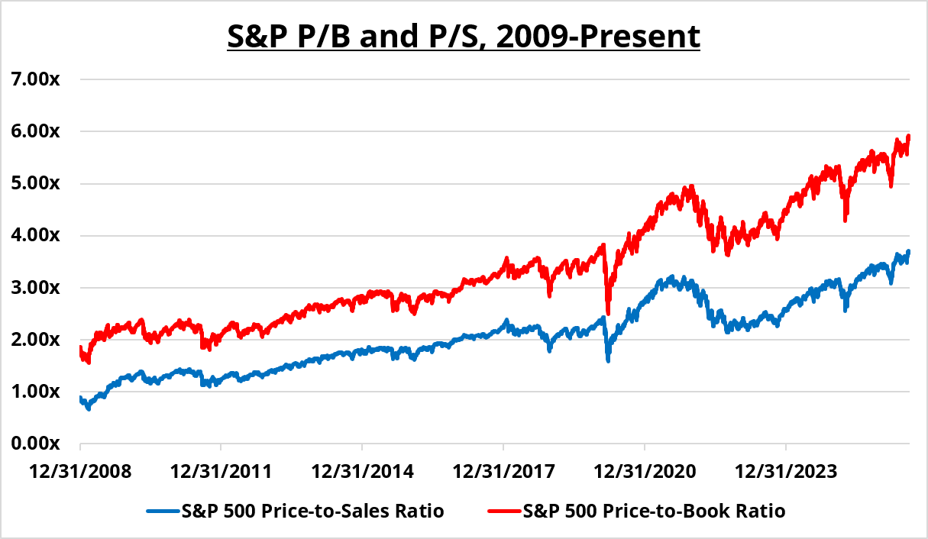
First, the S&P 500 index was hellaciously cheap at the bottom in 2009 and was pretty much left for dead. Second, it “led to your door” because interest rates fell off and on for 13 years. As rates fell and stock markets did less “winding,” investors became more emboldened. What could be better than getting rich on the low-cost and highly diversified S&P 500 Index? Now, 17 years after the bottom, S&P 500 investors gather in chat rooms (one this last week in The Wall Street Journal) to describe how brilliant they are and how foolish active stock pickers are.
Source: Bloomberg.
The problem is that, historically, the stock market has been a long and winding road. When it has unusual success for an extended period, and the price of money goes up, you get what the Beatles called, “A wild and windy night that the rain has washed away!” They go on to sing, “has left a pool of tears, crying for the day. Why leave me standing here? Let me know the way!”
Succeeding as a successful large-cap value manager is also explained in the song. “Many times I’ve been alone and many times I’ve cried.” However, being alone with 95% active share in a mania like the one we are in is exactly where we want to be when the long and winding road leads where it has always led in the past. Our goal is to “lead you back to the long and winding road” in common stocks, which our eight criteria define, and to avoid the glamour and excitement that have showered S&P 500 Index investors. Investors now own an index that is heavily concentrated in 15 of the 500 stocks and more vulnerable to mean reversion than at any time in my 46 years in the investment business.
As the song said, “Don’t keep me waiting here, lead me to your door.”
Play The Long Game,
William Smead
The information contained in this missive represents Smead Capital Management’s opinions, and should not be construed as personalized or individualized investment advice and are subject to change. Past performance is no guarantee of future results. Bill Smead, Chairman & CIO, wrote this article. It should not be assumed that investing in any securities mentioned above will or will not be profitable. Portfolio composition is subject to change at any time and references to specific securities, industries and sectors in this letter are not recommendations to purchase or sell any particular security. Current and future portfolio holdings are subject to risk. In preparing this document, SCM has relied upon and assumed, without independent verification, the accuracy and completeness of all information available from public sources. A list of all recommendations made by Smead Capital Management within the past twelve-month period is available upon request.
©2026 Smead Capital Management, Inc. All rights reserved.
This Missive and others are available at www.smeadcap.com

